📏 Rules & Requirements
1031 exchanges are powerful but strictly rule-bound.
Like-Kind Property Rule
Core RuleReplacement must be "like-kind" — broadly interpreted for real estate. A rental house can exchange for a commercial building, raw land for an apartment. Both must be U.S. real property held for investment or business.
Equal or Greater Value
ValueTo fully defer all taxes, acquire property of equal or greater value and reinvest all equity. Trading down triggers tax on the difference (boot).
45-Day Identification Window
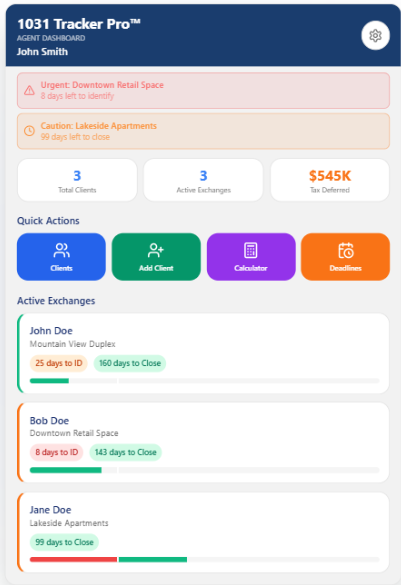
Critical DeadlineExactly 45 calendar days from closing to identify replacements in writing. No extensions — not for weekends, holidays, or illness.
180-Day Closing Window
Critical DeadlineMust close within 180 days of relinquished sale — or by the tax return due date, whichever is earlier. Filing an extension preserves the full 180 days.
3-Property / 200% / 95% Rules
IdentificationIdentify: (1) Up to 3 properties any value, OR (2) Any number ≤200% of relinquished value, OR (3) Unlimited properties if you close on ≥95% of total identified value.
Qualified Intermediary Required
QI RequiredIRS mandates a QI hold exchange funds. You cannot receive, pledge, borrow, or benefit from proceeds at any point — doing so triggers immediate tax on the entire gain.
Same Taxpayer Rule
EntityThe entity selling must be the entity buying. Sell as an individual, buy as an individual. Mid-exchange entity changes can invalidate the exchange.
Holding Period & Intent
HoldingNo IRS-mandated minimum, but most advisors recommend 1–2+ years to demonstrate investment intent. Quick resales after an exchange invite IRS scrutiny.
Get the Free 1031 Exchange Checklist
Enter your name and email and we'll send it right to you.

